On August 3, 2026, the seminar titled “Criminal Compliance Boundaries and Wealth Protection Under the New Offshore Trust Taxation Regulations” was successfully held. Co-hosted by the King&Capital Family Trust Legal Affairs Center and the King&Capital Criminal Defense Center, and co-organized by King&Capital’s Second Financial Department, Corporate and Compliance Department, and First Criminal Department, the event combined live online streaming with an in-person session. From three perspectives—tax system interpretation, operational practices, and criminal compliance— systematically analyzed the far-reaching impact of the new regulations on high-net-worth individuals and family wealth management structures, providing professional guidance and practical strategies for taxpayers to establish tax compliance systems and safeguard the security of business operations and personal assets.
The seminar was moderated by Attorney Teng Jie, a partner at Beijing King&Capital Law Firm. At the outset of the event, Attorney Xiao Shuwei, Senior Partner and Party Committee Secretary of Beijing King&Capital Law Firm, delivered opening remarks. Attorney Xiao Shuwei shared his profound insights into industry developments and extended a warm welcome to the attendees.
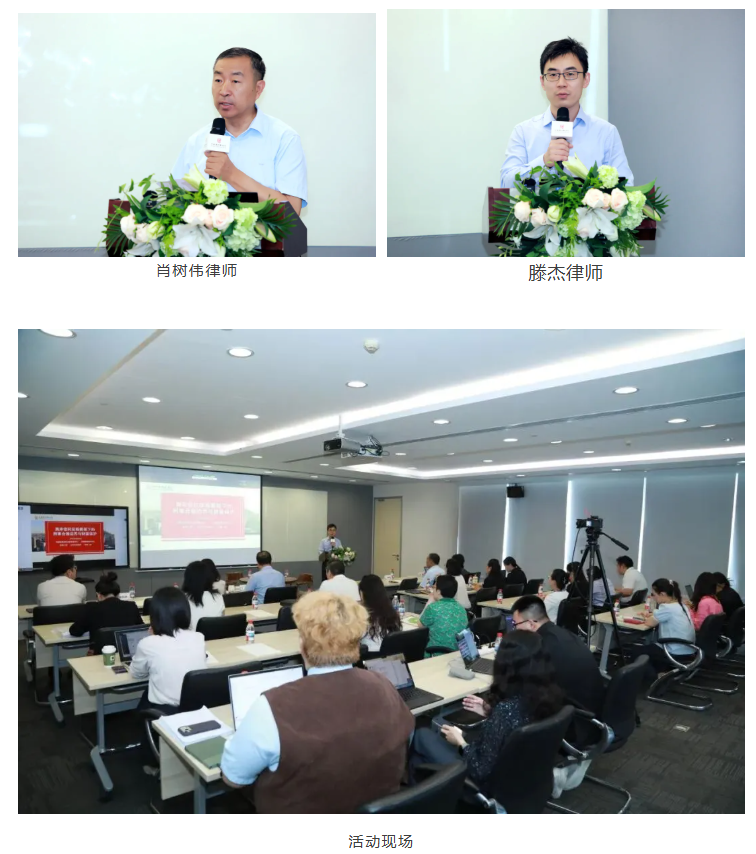
Event Venue
In-Depth, Multi-Dimensional Insights: Deconstructing Core Challenges in Offshore Trust Taxation
Director Gao Huiyun
The first speaker was Gao Huiyun, Senior Tax Law Advisor at Beijing King&Capital Law Firm and Executive Director of the King&Capital Family Trust Legal Affairs Center, who presented on the topic “Response Strategies Under the New Tax Regulations for Offshore Trusts.” Starting with the basic structure of offshore trusts, Director Gao Huiyun analyzed the taxation rules for the three stages—establishment, continuation, and termination—under the new regulations, point by point, using the typical case of the Lei Jun family trust holding shares in Xiaomi Group as an example.
She focused on explaining the application of anti-tax avoidance “look-through” rules during the trust’s existence—specifically, that income from offshore entities failing to meet substantive operational requirements will be directly attributed to resident individuals for taxation, thereby preventing the transfer of profits through offshore shell companies. At the same time, regarding common practical arrangements—such as “establishing a trust under the name of a Hong Kong resident but with actual control by a mainland resident, or placing assets into multi-layered nested companies”—she provided an in-depth analysis from the perspectives of CRS information exchange and the extension of tax jurisdiction. In the section on response strategies, she proposed a four-step approach: analyze whether the settlor qualifies as a Chinese tax resident; complete the review and filing of existing trusts within the 90-day window; assess the tax burden associated with unwinding the trust; and consider the feasibility of repatriating funds to establish a trust within China, along with arrangements for beneficiaries. She also noted that the new regulations draw on the deemed sale rule under Section 684 of the U.S. Internal Revenue Code, the deemed resident trust rule under Section 94 of the Canadian Income Tax Act, and Australia’s transferor trust look-through rule; in terms of tax burden, the Chinese system remains moderate compared to the trust tax regimes of other countries.
Attorney Wang Shuaifeng
Attorney Wang Shuaifeng, a partner and certified tax agent at Beijing King&Capital Law Firm, delivered a presentation on “Practical Operations for Existing Offshore Trusts During the 90-Day Window Period.” Attorney Wang Shuaifeng provided a detailed overview of the policy rationale and key timelines for the 90-day golden window period: According to Article 17 of Announcement No. 21, any unpaid individual income tax arising from the transfer of assets into an offshore trust between January 1, 2023, and December 31, 2025, as well as any unreported income tax during the offshore trust’s existence, must be reported and paid within 90 days from the effective date of the new regulations (i.e., by October 22, 2026), without incurring late payment penalties; After the grace period expires, a late payment penalty of 0.05% per day will be imposed, and false reporting or refusal to file may result in criminal liability.
Regarding practical implementation, Attorney Wang Shuaifeng provided a detailed explanation of the filing deadlines, rules for determining the competent tax authority, and the list of required documents for each of the seven categories of filing scenarios. He specifically noted that determining the competent tax authority involves multiple factors, including the place of registration of the primary domestic production and business operations enterprise, the location of domestic assets, and the place of habitual residence within China. For actual controllers of overseas-listed companies that control domestic enterprises through equity or contractual arrangements, accurately identifying the competent tax authority is the primary prerequisite for compliant filing. At the same time, given the complexity of tax matters involving offshore trusts, taxpayers should prepare in advance the necessary authorization and power-of-attorney documents, as well as overseas materials such as “notarization + legalization” or “notarization + supplementary certificate,” to ensure the smooth completion of filings within the designated window period.
Attorney Wang Yang
The third guest speaker was Wang Yang, a senior partner at Beijing King&Capital Law Firm and a Chambers-listed lawyer in the field of tax law. She delivered a special presentation titled “Determining the Nature of Undeclared Offshore Trusts and the Red Lines of Criminal Risk.” Attorney Wang Yang began by pointing out that “undeclared” is in itself a neutral fact; even in cases of failure to file on time, the legal consequences can vary drastically, depending on the taxpayer’s subjective intent and objective conduct.
Starting with the four elements of the crime of tax evasion under Article 201 of the Criminal Law—means, result, amount, and procedure—she provided a detailed analysis of the criteria for determining “means of deception or concealment” and “failure to file,” drawing on the “Interpretation on Several Issues Concerning the Application of Law in Handling Criminal Cases Involving Acts Harmful to Tax Administration” (Fa Shi [2024] No. 4) issued by the Supreme People’s Court and the Supreme People’s Procuratorate. Regarding the monetary thresholds, the 2024 judicial interpretation by the “Two Highs” adjusted the threshold for “relatively large amounts” in tax evasion offenses to 100,000 yuan, provided it accounts for more than 10% of the total tax payable, while “huge amounts” were set at 500,000 yuan. In the context of offshore trusts, the basis for calculating the “total tax payable”—particularly the treatment of liquidation proceeds and deemed distributions—directly affects whether the 10% threshold is met, making it the aspect requiring the most precise calculation and verification in criminal defense.
Attorney Wang Yang particularly emphasized the core value of the “exemption for first-time offenders” provision: if, after receiving a tax recovery notice from the tax authorities, a taxpayer voluntarily pays the back taxes, pays the late payment penalties, and accepts administrative penalties, criminal liability will not be pursued. This means that the 90-day grace period represents the opportunity with the lowest compliance cost. She also outlined four absolute red lines for criminal risk: forging trust documents or overseas account statements to evade audits; filing false returns or deliberately underreporting taxable income during the grace period; refusing to pay back taxes after receiving a collection notice from the tax authorities; and evading tax reporting again despite having two prior administrative penalty records within the past five years.
In-Depth Roundtable Discussion: Deriving Compliance Insights from Practical Challenges
The seminar then moved on to the roundtable forum, where discussions covered practical challenges such as the taxability of income retained overseas, the burden of proof for subjective intent in piercing the corporate veil of offshore entities, and the complexity of multi-stage cross-verification. Drawing on their extensive experience in tax-related criminal defense, financial dispute resolution, and cross-border wealth management, the panelists addressed the real challenges entrepreneurs face under the new offshore trust taxation regulations. They also engaged in forward-looking discussions on cutting-edge issues such as pathways for the compliant restructuring of family wealth structures, strategies for self-inspection and supplemental filing during the grace period, and synergistic mechanisms for tax compliance and criminal risk prevention, providing attendees with multidimensional professional perspectives and practical guidance.
Q
A
&
Teng Jie
Partner
Han Ruiqi
Attorney
Attorney Han, following the release of Announcement No. 21, I’ve noticed a very real phenomenon—many entrepreneurs are hesitating: “Should I file within 90 days or not?” Their biggest concern is: If I don’t file within 90 days, does that constitute tax evasion? If I do file but don’t report accurately, does that constitute tax evasion? Will the financial staff involved be considered accomplices if they report everything?
To understand this provision and determine whether to file within the 90-day period, I believe we can examine the following aspects:
I. Generally speaking, individual income tax issues arising from residents or non-resident individuals transferring assets into offshore trusts prior to January 1, 2023, are not covered by Announcement No. 21. As such, they are not subject to the 90-day filing deadline and do not require filing.
2. Although Circular No. 21 was issued and took effect on July 24 of this year, its regulatory effect generally took effect on January 1, 2023. Therefore, for personal income tax issues arising from residents or non-resident individuals transferring assets into offshore trusts on or after January 1, 2023, the 90-day filing requirement applies. If the return is filed within 90 days, no late payment penalty will be imposed, and only the corresponding tax will be collected; if the return is filed after 90 days, a late payment penalty will definitely be imposed.
III. According to the provisions of the *Tax Collection and Administration Law*, tax filing methods are divided into two categories: voluntary filing and filing upon notification by the tax authorities. Voluntary filing refers to taxpayers proactively reporting their tax-related circumstances to the tax authorities and submitting relevant tax-related materials or documents; filing upon notification by the tax authorities refers to the tax authorities legally notifying taxpayers to report their tax-related circumstances and submit relevant tax-related materials or documents to the tax authorities.
IV. Document No. 21 has been in effect for only a short time, and the 90-day filing period will pass in the blink of an eye. Furthermore, offshore trust situations are complex and involve voluminous documentation; the vast majority will also require notarization, authentication, and translation of foreign-language materials. If taxpayers do not have a thorough grasp of the essence of Document No. 21 or a comprehensive understanding of offshore trust circumstances, the success rate of voluntary filing will be cause for concern; If the competent tax authority determines that the filing is fraudulent, it is highly likely to be deemed tax evasion, with severe consequences.
5. Within the 90-day period, if the tax-related information voluntarily reported by a taxpayer is inaccurate—particularly in cases where the value of reported assets is significantly undervalued or certain income is omitted—the risk of being deemed tax evasion is very high, as this directly involves the authenticity of the filing and relates to non-payment or underpayment of taxes.
Q
A
&
Teng Jie
Partner Attorney
You Le
Attorney
Attorney You, I’d like to ask you: Will the issuance of Announcement No. 21 accelerate comprehensive legislation on the domestic trust tax system?
For a long time, the lack of a trust tax system has drawn widespread attention within the industry, and the need to clarify the trust tax system has been repeatedly mentioned in proposals regarding the revision of the Trust Law during the Two Sessions. The issuance of Announcement No. 21 has initiated the legislative process for the trust tax system and will also accelerate the legislation of the domestic trust tax system. The role of Announcement No. 21 in accelerating the legislation of the domestic trust tax system is reflected in: 1. Setting a policy precedent; 2. Creating a driving force; 3. Guidance of expectations. However, given the complexity of the trust tax system, legislation cannot be completed in one fell swoop and must be advanced in phases.
If the domestic trust tax system is implemented, will the tax treatment of domestic trusts and offshore trusts converge?
The tax treatment of domestic trusts and offshore trusts may be consistent in principle and framework, but there will be certain differences at the operational level.
Areas of convergence: First, a full-lifecycle taxation framework, with all stages—establishment, existence, distribution, and termination—included within the scope of taxation; second, the substance-over-form principle, determining the taxable entity based on who contributes capital, who exercises control, and who benefits; third, the principle of avoiding double taxation; fourth, the trustee primarily bearing the obligation to report information; and fifth, a uniform tax rate of 20 percent.
Differences: First, offshore jurisdictions apply “taxation upon transfer upon transfer-in,” while onshore jurisdictions are expected to establish “tax deferral for non-transactional transfers”; second, during the trust’s existence, offshore trusts are taxed regardless of whether trust benefits are distributed, whereas onshore jurisdictions may adopt a refined classification system for taxation based on actual circumstances; third, offshore jurisdictions uniformly apply “look-through” rules, with the settlor generally serving as the taxpayer, while onshore jurisdictions will apply different rules based on classification; Fourth, offshore taxation is non-discriminatory, whereas onshore trusts with social value—such as those for public welfare or special needs—may receive differentiated treatment, including tax deferral, deductions, or tax exemptions.
What advice do you have for entrepreneurs considering the establishment of an onshore family trust?
The main advice for entrepreneurs considering the establishment of an onshore family trust is as follows:
1. If you wish to use a family trust to isolate risks for wealth preservation and succession, it is better to establish it sooner rather than later; do not wait until risks arise to set up a trust.
2. View the function of a trust correctly; the focus should shift from “tax optimization” to “risk isolation, wealth preservation, and succession.”
3. Ensure the legality of the source of trust assets; the property placed in the trust must be lawful, fully taxed, and clearly identifiable assets held in the settlor’s name.
4. Carefully draft provisions regarding the settlor’s reserved rights.
5. Maintain complete trust records and recognize the importance of proper record-keeping.
Q
A
&
Teng Jie
Partner
Zhang Yanfei
Partner
Attorney Zhang, as a lawyer specializing in offshore trusts who has long served family clients and designed offshore trusts for many of them, you understand entrepreneurs’ genuine concerns better than anyone. When Announcement No. 21 was issued, many clients’ first reaction was, “The trust was a waste of time” or “Let’s just revoke it immediately.” But I’d like to ask you a more fundamental question: If we set aside tax considerations for the moment, what was the original purpose of clients establishing offshore trusts in the first place? Under Announcement No. 21, does the asset isolation function of trusts still exist?
For high-net-worth clients, the powerful advantages of offshore trusts lie in their asset isolation, privacy protection, flexible wealth succession planning and family governance capabilities, as well as the convenience they offer for global asset allocation.
Some clients worry that since trust income is subject to tax at the settlor level, does this mean the trust’s asset protection function is lost? This is a common misconception. Announcement No. 21 designates the settlor as the taxpayer, reflecting a method of tax administration based on the “substance-over-form principle” under tax law. However, this does not affect the independence of the trust property. Once a trust is validly established, its legal independence is firmly established and will not be negated simply because the settlor is designated as the taxpayer.
Do you have any recommendations for clients regarding this situation?
First, should offshore trusts still be established? I suggest that rather than pursuing complex structures, we should return to the most fundamental functions of a trust. The core value of offshore trusts lies in asset protection, risk isolation, and the targeted transfer of wealth. With the official implementation of Announcement No. 21, the sole purpose of tax savings or tax avoidance is no longer a sufficient reason for establishing an offshore trust.
Second, is it necessary to dismantle existing trust structures? If calculations show that the overall tax burden of an offshore trust over its entire lifespan is significantly higher than the tax costs associated with assets held in a domestic family trust, then dismantling it is indeed an option that warrants serious consideration. However, dismantling is not simply a matter of termination; supplementary tax filings for historical tax liabilities must be completed within the 90-day filing window. At the same time, Announcement No. 21 explicitly stipulates that upon termination of a trust, the liquidation proceeds from all trust assets must be uniformly subject to a 20% personal income tax rate under the category of “interest, dividends, and profit distributions.” Only after historical tax filings have been completed and liquidation taxes settled can the termination process proceed in a legal sense, and this must be carried out strictly in accordance with the terms of the trust deed. Furthermore, it is recommended to take advantage of a tax benefit provided by the new regulations: taxes payable arising from the liquidation may be paid in installments over a five-year period.
Third, if you decide to retain an offshore trust, you must ensure tax compliance; it is recommended to conduct a thorough review of the trust structure. First, re-evaluate the tax residency status of the settlor and beneficiaries. Clients who have obtained residency in other countries but whose core business operations remain in China must acknowledge the possibility of being deemed Chinese tax residents and take proactive steps to ensure compliance. Second, analyze the nature of each tier of companies within the trust structure to determine whether they are active business entities or passive non-operating entities, whether they are subject to look-through scrutiny, and whether this would result in direct tax liabilities. For “shell” companies that typically serve only as holding vehicles, consider injecting substantive business operations to reduce the risk of direct look-through. Third, make full use of the 90-day filing window to systematically review past transactions and conduct a review of the underlying assets.